The comparison is based on your figures
Not on a standard case. The gap between two tax regimes depends entirely on the level of costs and on whether there is a loan: a generic example tells you nothing about your situation.
The choice of tax regime is the decision that weighs most on a property’s net yield, and it is the one landlords most often make by default — because comparing means calculating the same thing five times with different rules.
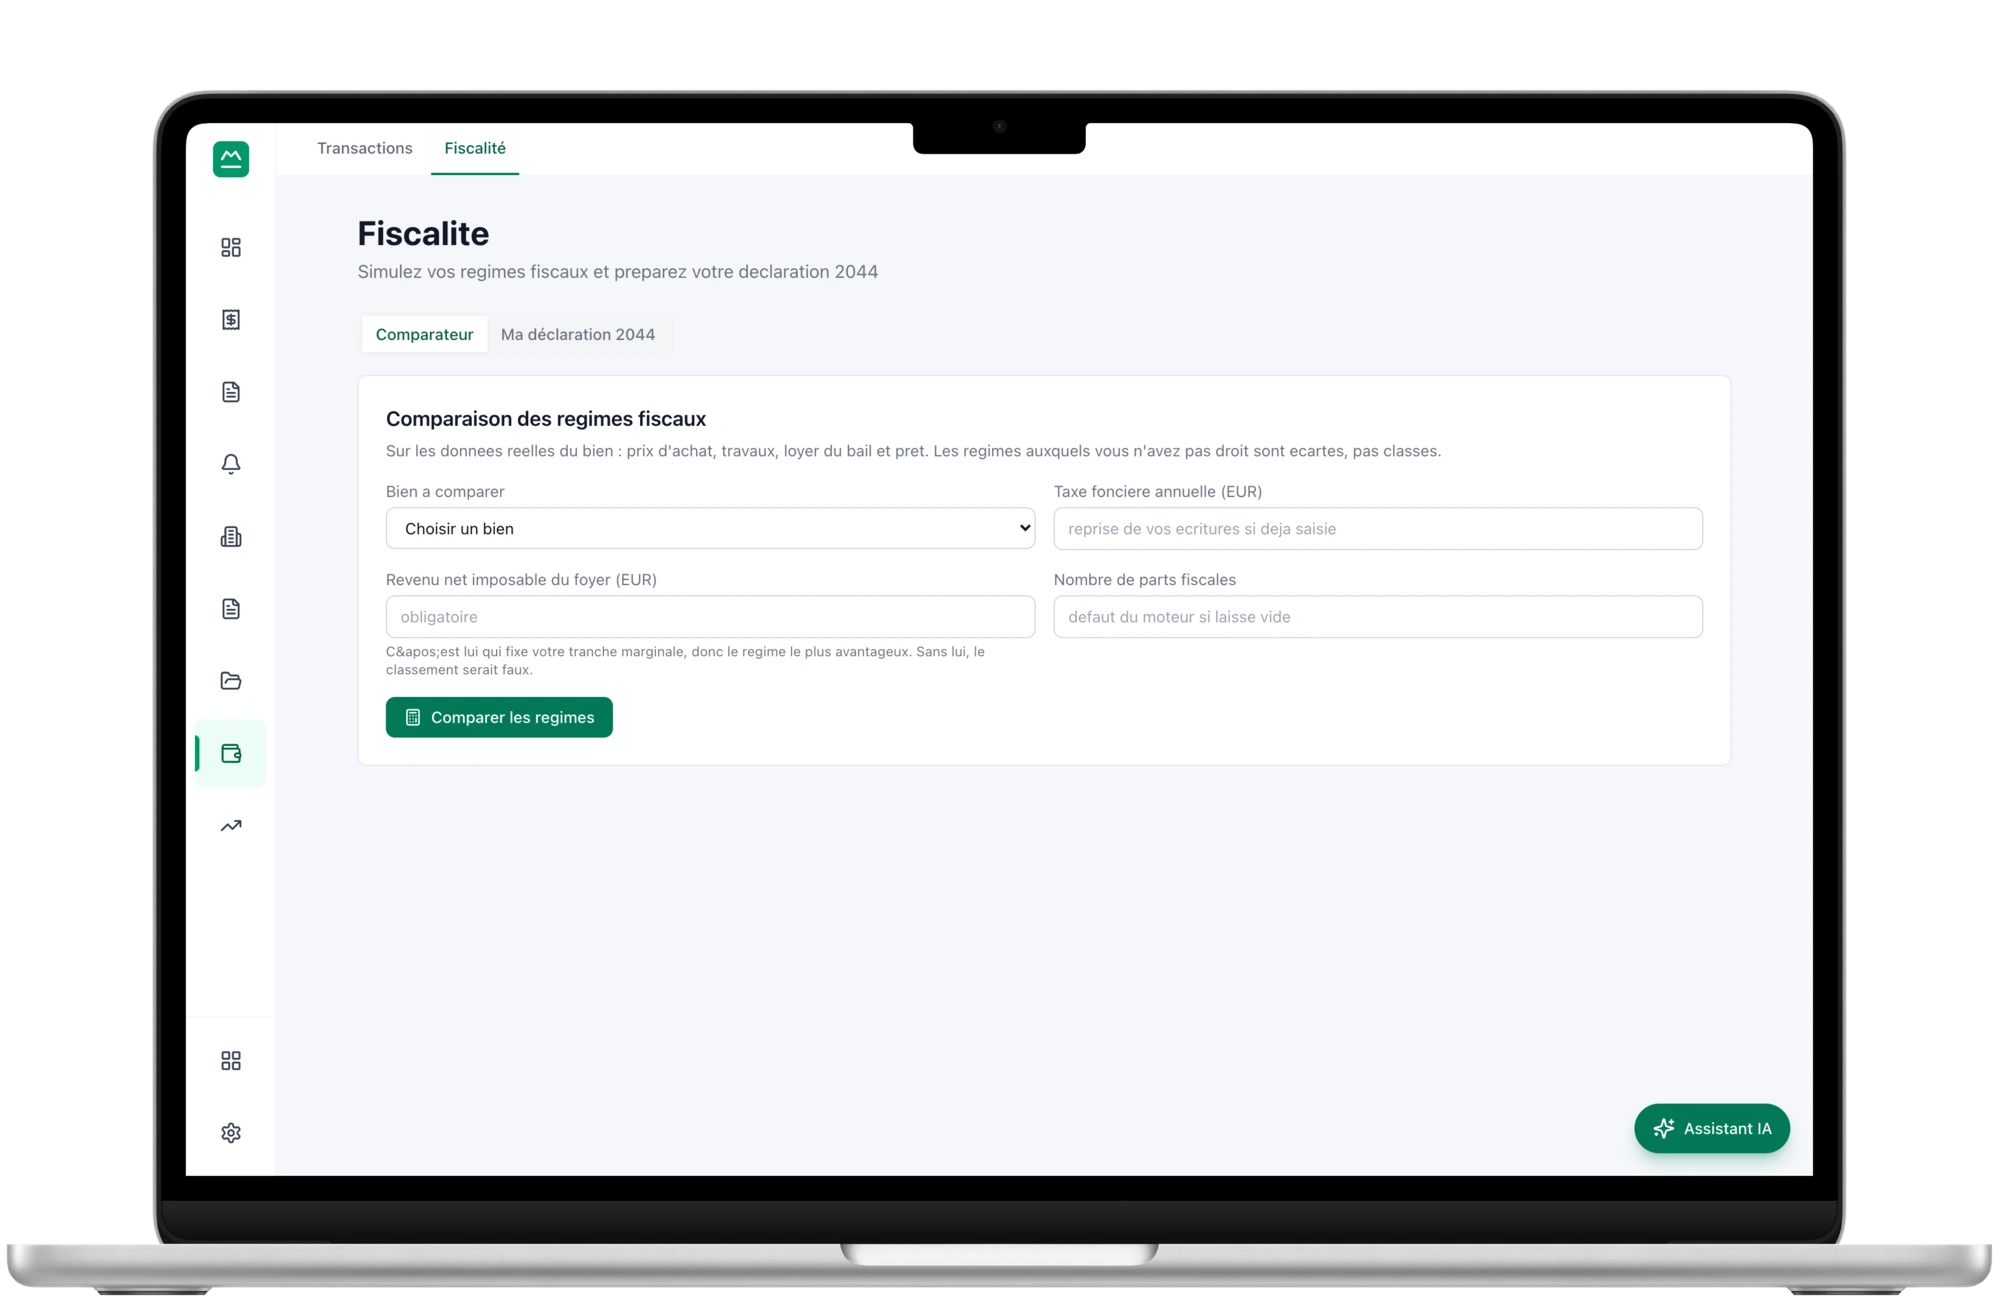
The micro regime is simple and requires no bookkeeping; the actual-expenses regime lets you deduct real costs and create a deficit that can be carried forward. Depending on the level of costs, whether there is a loan and the landlord’s tax band, the annual difference between the two often exceeds a month’s rent. Yet the micro regime applies automatically below the thresholds: doing nothing is a choice, and it is the one the vast majority of owners make — without ever having compared. Some commitments are also multi-year, which means an option taken without calculation is paid for several years running.
An unfurnished letting does not come under the furnished-letting regime, and turnover thresholds close access to the micro regime above a certain level of income. Eligibility is checked before any calculation: offering an inaccessible regime is the most common flaw of simulators.
Rent collected, charges by category, loan interest calculated from the repayment schedule, property tax looked up in your entries. These are your figures, not averages.
Property tax is looked up in the entries of the last twenty-four months and never guessed. If it is missing, the comparison stops and names the missing field — a comparison tool that assumes a value produces a ranking of regimes that has nothing to do with you.
micro-foncier, réel foncier, LMNP micro-BIC, LMNP réel and SCI subject to corporation tax: taxable income, estimated tax, effective rate. The ranking covers the same year and the same costs — without this common basis, the gap between two regimes means nothing.
Box-by-box carry-over, totals per property, and a comparison between the micro and real regimes on your figures for the year. An exportable summary is archived — it is not a filed return, it is a data-entry aid. For an SCI subject to income tax, the amounts of the 2072-S and its schedules are allocated building by building, then partner by partner.
Not on a standard case. The gap between two tax regimes depends entirely on the level of costs and on whether there is a loan: a generic example tells you nothing about your situation.
A furnished-letting regime is not offered for an unfurnished letting, and the thresholds are applied. That is what distinguishes a usable comparison from a four-column table.
The same rent collected, the same costs, the same calculated interest. Your tracking and your tax return therefore cannot contradict each other — which is exactly what happens when the two live in separate files.
art. 32 of the French General Tax Code
Irrevocable for three years: an option taken without calculation therefore commits three tax years. And the flat-rate allowance replaces ALL costs — a heavily indebted landlord who stays on the micro regime loses the deduction of their interest without ever seeing the missing line.
art. 156 I 3° of the French General Tax Code
The distinction between a deficit arising from costs and a deficit arising from interest is systematically ignored in self-prepared calculations. It changes the year’s tax saving, sometimes from everything to nothing.
art. 50-0 and art. 155 of the French General Tax Codedisputed point
Letting furnished changes the category of income, not just the rate of allowance. The thresholds, the reporting obligations and the treatment of deficits differ — and the ceilings have been changed several times in recent years, notably for furnished tourist lets.
art. 197 of the French General Tax Code; art. L. 136-6 of the French Social Security Code
The optimal regime therefore depends on your marginal tax band, and it can change in the year your other income changes. A “best regime” calculated once and for all is an answer to a question that keeps moving.
Property tax is looked up in your entries, never estimated. Without it, the comparison stops and names the field to complete. A ranking of regimes built on an assumed value is a ranking that has nothing to do with you.
No tax return package, no depreciation for furnished lettings, no electronic filing with the tax authority. That is chartered accountants’ work, outside the scope of the product, and we do not announce it.
The comparison informs a decision; it does not commit to one. Multi-year options, changes of regime during ownership and the effects on resale call for a professional who sees your whole situation.
Included from the Essentiel tier.
Five: micro-foncier, réel foncier, LMNP micro-BIC, LMNP réel and SCI subject to corporation tax. The engine calculates more, but we only put forward those that concern the great majority of private landlords.
It prepares the box-by-box carry-over and an exportable summary, based on the rents actually received and the expenses recorded. For an SCI subject to income tax, it also allocates the amounts of the 2072-S, of its per-building schedule and of its per-partner schedule; the share each partner carries over to their own 2044 follows from it to the cent. It does not calculate the tax and sends nothing to the tax authorities: it is a data-entry aid, not an online tax return.
No, and it is not planned: no tax return package, no depreciation for furnished lettings, no electronic filing. That is work for a chartered accountant, and we would rather not announce it than sketch it.
Because a key piece of data is missing — most often the property tax, which we look for in your entries and never guess. A comparison tool that assumes a value ranks tax regimes for a property that is not yours.
Yes, as soon as your other income or your level of costs changes, since income tax follows a progressive scale. And opting for the réel regime commits you for three years on unfurnished lettings: it is a decision to take with a calculation, not by default.
Costs deducted, total cost in the denominator. One single definition of yield across the whole product.
Costs-to-rent ratio on rents actually received, a 24-month series and a rolling average — without which October’s property tax looks like a drift.
Generated from your repayment schedule, so it ages on its own. The net value follows from it, estimated selling costs deducted.
Calculated on actual spend, with the itemisation by category and the allocation method required by law.
Content reviewed on 2026-08-06.
At launch: a 7-day trial on your real properties, card required.